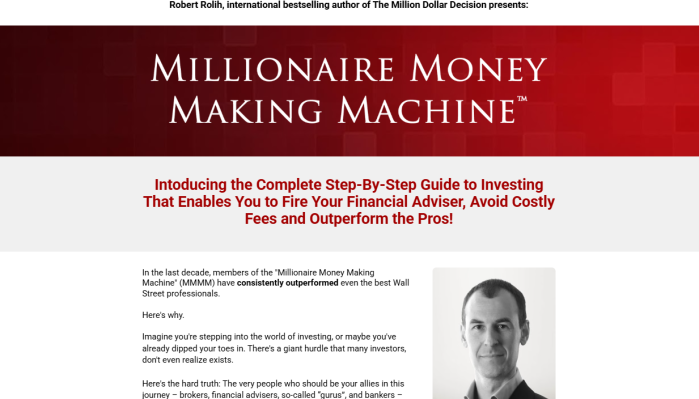
Robert Rolih – Millionaire Money Making Machine: A Field Guide to Managing, Protecting, and Growing Your Money
Money management is not just about how much you earn. Two people can have similar incomes and end up in very different financial positions because of the way they spend, save, protect, and invest what they have.
One person may accumulate assets steadily, understand the costs attached to financial products, and make decisions with a long-term plan in mind. Another may earn well but lose ground through unnecessary fees, unsuitable insurance, poorly understood investments, or a lack of financial organization.
That difference is at the center of Robert Rolih’s Millionaire Money Making Machine, often shortened to MMMM.
Despite its attention-grabbing name, this program is not primarily about launching an online business or creating an automated sales funnel. Its advertised subject is personal finance and investing. The material is designed to help learners understand the financial decisions that shape long-term wealth, from managing everyday money to choosing investments and thinking about retirement.
The course takes a broad approach. It covers financial literacy, insurance, precious metals, index funds, bonds, ETFs, cryptocurrency, portfolio allocation, and goal setting. Rather than treating these as completely separate subjects, it presents them as parts of a wider financial-management framework.
Start with financial understanding, not investment products
The first part of the program is called Increase Your Financial Wisdom.
This is an important starting point because choosing an investment before understanding your own financial position can lead to poor decisions. Before comparing funds, bonds, or other assets, it helps to know what money is coming in, what is going out, what you owe, and what you are trying to accomplish.
The advertised opening lessons introduce financial literacy and the relationship between income, money management, and long-term financial progress. They also cover what the program calls the three areas of financial wisdom:
- World view
- Personal financial statement
- Money management
These topics encourage a more complete view of personal finances. Your financial position is not defined by salary alone. Expenses, debt, savings, financial obligations, and the way you allocate available money all matter.
For someone who has never organized a personal financial statement, this type of foundation can be useful. It creates a clearer picture of the starting point before any investment strategy is considered.
The course also discusses the idea that financial success depends heavily on how money is managed, not simply on how much a person earns. That is a useful principle to examine, although individual outcomes still depend on income, costs of living, family responsibilities, economic conditions, and many other factors.
FAQ
1. What is Robert Rolih’s Millionaire Money Making Machine?
It is a personal finance and investment education program covering financial literacy, money management, insurance, precious metals, long-term investing, ETFs, bonds, cryptocurrency, asset allocation, and financial goal setting.
2. Who created the Millionaire Money Making Machine?
The program is associated with Robert Rolih, an entrepreneur and financial educator. Some third-party product listings misspell his surname as “Rolith.”
3. What are the main topics covered?
The advertised curriculum includes five broad areas: financial wisdom, financial protection, long-term investing, return-enhancement strategies, and financial goal setting.
4. What is the A.R.M.O.R. formula?
It is a framework presented in the course for evaluating insurance and financial protection decisions. Its advertised principles include assessing risks, reviewing insurers, separating investments, optimizing costs, and reading policy terms carefully.
5. What is the G.R.A.I.N. system?
It is the course’s long-term investing framework, covering asset selection, reducing investment costs, cost averaging, evaluating financial advice, and maintaining a portfolio over time.
6. Does the course cover ETFs and index funds?
Yes. The advertised curriculum includes ETF selection, index funds, bonds, the Satellite Strategy, and practical lessons on purchasing investments through online brokers.
Protect the financial foundation before trying to grow it
The second stage is called Protect Yourself.
Investment discussions often focus on potential returns. But financial planning also involves thinking about what could go wrong and how much of your existing financial position is exposed to unnecessary risk.
This section introduces the A.R.M.O.R. formula, an approach the course uses to discuss insurance decisions and financial protection.
The advertised material includes:
- Assessing risk factors
- Reviewing insurance companies
- Keeping investments separate
- Optimizing costs
- Reading the small print
The practical idea is to examine insurance products carefully rather than assuming that a familiar or heavily promoted policy is automatically the right choice.
Insurance can be difficult to evaluate because policies may differ in coverage, exclusions, charges, commissions, surrender conditions, and other details. Understanding those elements can help consumers ask better questions before committing to a product.
The course also discusses precious metals, particularly gold and silver. Its outline includes lessons about the reasons people buy these assets, common purchasing mistakes, and different ways to buy gold.
This makes the section broader than an insurance overview. It asks learners to consider how they protect their financial position and how they evaluate assets that are often discussed as stores of value.
One important point for buyers: insurance requirements vary by country, and a product suitable for one person may not be appropriate for another. The course should be treated as educational material, not as a substitute for independent advice about your own coverage.
Build the long-term portfolio: The G.R.A.I.N. system
The third part of the program is titled Grow Your Golden Goose and focuses on long-term investing.
This is one of the most substantial areas in the advertised curriculum. It introduces the G.R.A.I.N. system, a framework built around five principles:
- Grow the right assets
- Reduce costs
- Avoid heights
- Ignore advisers
- Never kill the goose
The framework emphasizes selecting suitable assets, paying attention to investment costs, and thinking about how a portfolio can be maintained over time.
A major topic here is index funds and ETFs. These investment vehicles can provide exposure to a collection of securities through a single fund, but their risks, fees, holdings, and structures vary. Understanding those differences is important before deciding whether a particular fund belongs in a portfolio.
The advertised lessons cover Robert’s personal ETF selection, the Satellite Strategy, bond selection, and purchasing index funds and bonds through online brokers.
There is also country-specific material for investors in the United States, United Kingdom, European countries, and other markets. That matters because available funds, tax treatment, broker access, and regulations can differ considerably between jurisdictions.
For learners who have heard about index investing but are unsure how to compare funds, this section provides a route into the subject. It encourages attention to costs, asset selection, diversification, and the practical mechanics of investing.
The material also discusses dollar-cost averaging and long-term investment behavior. These are concepts worth understanding, particularly for people who want to avoid making every investment decision based on short-term market movements.
However, no investment approach removes market risk. Index funds and bonds can lose value, and a portfolio that suits one person’s time horizon or risk tolerance may be unsuitable for another.
Explore return-enhancement ideas without confusing them with guarantees
The fourth stage is called Accelerate Your Returns.
This part introduces strategies that go beyond the basic long-term portfolio discussion. The advertised material includes short-term investing concepts, cryptocurrency, and tools or approaches described as portfolio boosters.
The available third-party course inventory also identifies lessons on the crypto market and using exchanges such as Kraken and Binance. These platform-specific demonstrations may be useful for understanding how certain exchange interfaces work, but buyers should check the age of the recordings and whether the platforms’ current features still match the lessons.
Cryptocurrency deserves particular caution. Digital assets can be volatile, exchanges carry operational and custody risks, and market conditions can change quickly. A lesson explaining how to use an exchange does not establish that buying a particular asset is appropriate.
The program’s promotional material also refers to buy-and-sell signals and investment updates. These should not be interpreted as guaranteed profitable recommendations. Any historical performance claim needs independent verification, and past performance does not predict future results.
For a learner, the useful takeaway from this section is to understand the difference between a long-term investment plan and higher-risk strategies that may require closer attention. They should not be treated as interchangeable.
Put the pieces together with asset allocation
Knowing about ETFs, bonds, gold, or cryptocurrency is only part of investment planning. Another important question is how different assets fit together.
The advertised Asset Allocation Action Plan addresses this issue.
Asset allocation means deciding how much of a portfolio to place in different categories, such as stocks, bonds, cash, and other assets. The decision can influence both the potential growth and the volatility of a portfolio.
The course inventory lists lessons covering:
- Asset allocation basics
- Retirement and long-term growth
- Allocation for other financial goals
- Creating an individual action plan
The curriculum also refers to allocation based on age and risk appetite.
This is an important subject because a portfolio should not be designed around a single universal formula. Someone investing for retirement decades away may have a different time horizon from someone saving for a home purchase in a few years. Income stability, existing savings, liabilities, and the ability to tolerate losses also matter.
A structured approach to asset allocation can help learners think beyond individual investment products and consider the portfolio as a whole.
Still, an educational course cannot determine the correct allocation for every buyer. Personal circumstances and local tax and regulatory rules should be considered before making actual investment decisions.
Financial goals: Make the plan meaningful
The fifth stage is titled Dream Big and Share.
This section moves away from the technical side of investments and looks at financial goals, planning, and execution.
The advertised lessons discuss seven common goal-setting mistakes, the F.A.S.T. goal-setting framework, strategy, productivity, and getting things done.
This is a useful addition because financial education does not automatically lead to action. Someone may understand the basics of budgeting or investing but still struggle to follow a plan consistently.
Setting clear goals can help give financial decisions a purpose. Retirement, education, home ownership, business plans, and financial security are very different objectives. Each may involve a different time horizon and savings requirement.
The program’s focus on execution encourages learners to turn broad ambitions into more defined actions. That can mean reviewing expenses, setting savings targets, organizing investments, or establishing a regular financial review routine.
The important distinction is that goal-setting frameworks can improve organization, but they cannot guarantee that a financial target will be reached. Economic conditions, personal circumstances, and investment performance remain outside an individual’s full control.
What about the updates and ongoing support?
The sales description also advertises a Stay Updated, Stay Ahead package.
The listed features include live online sessions twice a year, email updates, buy-and-sell signals, and the ability to ask questions through the online library or email.
These features may be relevant to people who want more than a fixed collection of recorded lessons. Financial markets and investment products change, so updated information can matter.
However, there is an important distinction between the original course curriculum and an ongoing membership or update service. The current availability, frequency, duration, and eligibility for these features should be checked directly with the seller. Older recorded market updates are historical material, not current market guidance.
The available third-party inventory lists recordings of market updates and seminars dating from earlier years, including crypto and market commentary. These can provide historical context, but they should not be presented as current investment signals.
Who may find Millionaire Money Making Machine useful?
The program is most relevant to people who want a broad introduction to personal finance and investing rather than a narrow course about one investment product.
Beginners in personal finance may appreciate the progression from understanding their financial position to learning about asset protection and investment choices.
Long-term investors may be interested in the sections on index funds, ETFs, bonds, diversification, and asset allocation.
People reviewing insurance products may find the A.R.M.O.R. framework useful as a starting point for examining costs, policy terms, and risk coverage.
Investors interested in precious metals or cryptocurrency may find the relevant sections useful for learning terminology and understanding the approaches discussed, while recognizing that these assets involve different risks.
People planning for retirement may benefit from the discussion of long-term portfolios, asset allocation, and financial goals.
It may be less suitable for someone looking for day-trading signals, a guaranteed investment strategy, a personalized financial plan, or a course about building an online income business.
A few things to check before buying
The title is ambitious, and the sales copy includes strong claims about investment outperformance and financial results. These should be treated as promotional claims unless supported by independently verifiable evidence.
Before purchasing, it is sensible to check:
- Whether the advertised live sessions and email updates are currently active.
- Whether the latest market seminars are included in the specific version.
- Which country-specific investing lessons are available.
- Whether platform demonstrations still reflect current broker and exchange interfaces.
- The access duration, delivery method, and refund terms.
It is also worth remembering that the course’s framework is not a substitute for regulated financial advice. Insurance, tax, retirement, and investment decisions may require local professional guidance.
Final assessment: A broad personal finance education framework
Robert Rolih’s Millionaire Money Making Machine is a broad personal finance and investing program organized around financial understanding, protection, long-term investing, return-enhancement ideas, and goal setting.
Its main appeal is the range of subjects brought together in one curriculum. Instead of focusing exclusively on stock selection or cryptocurrency, it also addresses money management, insurance, precious metals, ETFs, bonds, and asset allocation.
For someone who wants to become more informed about these areas and develop a more structured way to think about personal finances, the course may provide a useful educational starting point.
The most important thing is to approach the material with realistic expectations. No course can guarantee millionaire status, outperform the market, or remove investment risk. The value of financial education is in understanding the choices available, recognizing the risks, asking better questions, and making decisions that fit your own circumstances

Reviews
There are no reviews yet.